Boat loan rates can vary from one borrower and watercraft to another. Your available Annual Percentage Rate, commonly called APR, may depend on your creditworthiness, loan amount, repayment term, down payment, and the boat’s age, value, and condition.
Understanding these factors can help you compare financing offers and avoid assuming that every advertised rate will apply to every boat or borrower.
What Is a Boat Loan Rate?
A boat loan rate affects how much interest you pay to borrow money for a new or used watercraft. Boat loan rates are commonly advertised as an APR, which expresses the yearly cost of borrowing as a percentage.
Your APR works with the loan amount and term to determine the required monthly payment and total interest. A lower APR can reduce the cost of borrowing, but the rate is only one part of the loan.
When comparing boat financing, review:
- APR
- Amount financed
- Loan term
- Monthly payment
- Total interest
- Total of all payments
- Down payment requirements
People Driven Credit Union publishes its current rate ranges and available terms on the PDCU boat loan rates table. Rates are subject to change, and your actual APR and term will depend on your application and the watercraft being financed.
1. Creditworthiness
Your creditworthiness is one of the factors a lender may use to determine your boat loan rate. It reflects how you have managed borrowed money and other financial obligations.
A lender may review information such as:
- Payment history
- Amounts currently owed
- Credit account history
- Recent credit applications
- Income and existing monthly obligations
- Ability to repay the requested loan
A credit score can help summarize information from your credit report, but it does not tell the entire story. Lenders may evaluate your complete application rather than relying on one number.
Before applying, review your credit reports for information that may be inaccurate. Paying bills on time and reducing outstanding balances may strengthen your overall financial profile, although no single action guarantees a particular rate.
2. Loan Amount
The amount you borrow may affect the boat loan rates and terms available to you. Lenders consider the requested loan amount in relation to your ability to repay and the value of the boat securing the loan.
Your amount financed may include more than the boat’s listed price. It can be affected by:
- Purchase price
- Down payment
- Trade-in value
- Existing trade-in loan balance
- Motor or trailer included in the purchase
- Optional equipment or products added to the transaction
Borrowing more can increase your monthly payment and total interest. It can also change which loan terms are available.
Ask the dealer or private seller for an itemized purchase agreement so you understand how the requested loan amount was calculated.
3. Loan Term
The loan term is the amount of time you have to repay the loan. Available boat loan rates may vary by term.
Shorter Boat Loan Terms
A shorter term generally produces a higher monthly payment because you repay the balance across fewer months. It may reduce the total interest paid over the life of the loan.
Longer Boat Loan Terms
A longer term generally produces a lower monthly payment. It may carry a different APR and increase total interest because the balance remains outstanding longer.
Do not select a loan based only on the monthly payment. Compare the APR, monthly payment, term, total interest, and total of payments.
People Driven Credit Union offers different rate ranges based on the selected term. The terms available to an individual borrower may also depend on the amount financed and the watercraft’s age and value.
4. Boat Age
The age of a boat can affect its financing. Newer boats may qualify for different rates or terms than older watercraft because age can influence value, condition, useful life, and resale potential.
PDCU’s current rate information explains how boat age may affect the applicable rate. Financing for significantly older boats may be limited or considered individually.
If you are considering a used boat, confirm its model year before agreeing to a purchase. Ask PDCU whether the boat’s age will affect the available rate or term.
Age alone does not determine whether a boat is a good purchase. A properly maintained older boat could be in better condition than a newer boat that was neglected. Maintenance records and an independent inspection can provide useful information about the watercraft’s actual condition.
5. Collateral Value and Condition
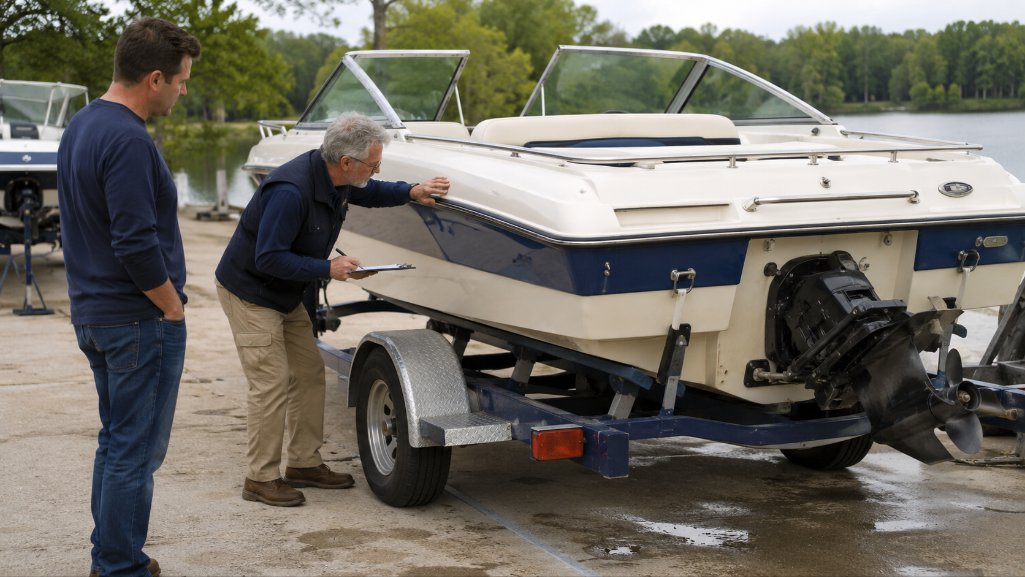
A boat loan is generally secured by the watercraft being financed. This means the boat serves as collateral for the loan.
The lender may compare the requested loan amount with the boat’s value. This relationship is called the loan-to-value ratio, commonly shortened to LTV.
The boat’s collateral value may depend on:
- Year, make, and model
- Overall condition
- Engine type and hours
- Maintenance history
- Included motor, trailer, and equipment
- Current market information
- Existing damage or needed repairs
If the purchase price is substantially higher than the boat’s supported value, the lender may not be able to finance the full amount. A larger down payment or a lower purchase price may be needed.
For an older or more complex boat, consider an independent marine inspection or survey. A survey can provide information about the boat’s condition and estimated value, but it does not guarantee financing or eliminate every purchasing risk.
6. Down Payment
A down payment reduces the amount you need to borrow. It can also lower the loan-to-value ratio by creating more equity in the boat at the beginning of the loan.
A lower requested loan amount may reduce your monthly payment and total interest. Depending on the application and watercraft, a down payment may also affect the financing options available.
A down payment does not automatically guarantee a lower boat loan rate. The lender will still consider your creditworthiness, loan term, collateral value, and other application details.
Before using a large portion of your savings, account for the other costs of boat ownership. You may need money for insurance, registration, storage, maintenance, winterization, safety equipment, and unexpected repairs.
7. Automatic Payments
Some lenders offer an interest rate discount when borrowers make automatic loan payments from an eligible account.
PDCU currently offers a rate discount on eligible loans when automatic monthly payments are made from a People Driven Credit Union checking or savings account. The discount is already included in the advertised “as low as” boat loan rate.
Review the current PDCU boat loan rates and automatic payment requirements for the latest information. Ask a representative what you must do to qualify and maintain the discount.
Automatic payments can help keep payments on schedule, but you should still review your account regularly. Make sure sufficient funds are available before each withdrawal and confirm that the payment was processed correctly.
How Boat Loan Factors Work Together
Lenders do not necessarily evaluate each rate factor in isolation. Your available boat loan rate may reflect the complete transaction.
For example, an application could involve:
- A strong borrowing profile
- An older boat
- A longer repayment term
- A large requested loan amount
- A down payment that reduces the loan-to-value ratio
One factor may strengthen the request while another adds risk. This is why two borrowers purchasing different boats may receive different rates or terms, even when the purchase prices are similar.
Advertised Boat Loan Rates vs. Your Actual Rate
An advertised “as low as” rate represents the lowest available rate under specific conditions. It does not mean every applicant or boat will qualify for that APR.
Your actual boat loan rate may be different based on:
- Your completed application
- Creditworthiness
- Amount borrowed
- Loan term
- Boat age, type, value, and condition
- Loan-to-value ratio
- Eligibility for an automatic payment discount
Review the qualifications and disclosures connected to any advertised rate. A lower advertised APR does not help if the boat, term, or application does not meet the required conditions.
How to Compare Boat Loan Rates
Request enough information to compare financing offers on equal terms. A useful comparison includes:
- The same purchase price
- The same down payment
- The same amount financed
- The same or similar loan term
- The APR
- The monthly payment
- The total interest
- The total of all payments
Be careful when comparing offers with different terms. A loan with a longer term may have a lower monthly payment but a higher total borrowing cost.
Use the PDCU boat loan calculator to estimate how different rates, loan amounts, down payments, and terms could affect your payment and total interest.
Can Boat Loan Pre-approval Tell You Your Rate?
Boat loan pre-approval can provide an estimate of the rate and terms that may be available before you select a specific watercraft. It can also help you establish a shopping budget and compare boats within that range.
Pre-approval is not final approval. The available rate or term may change after the lender reviews the selected boat, final purchase price, supported value, and updated application information.
You can apply with People Driven Credit Union before choosing a specific boat. After you submit your application, a PDCU loan specialist will contact you.
Learn more about pre-approval for boat loans.
Review Current PDCU Boat Loan Rates
People Driven Credit Union offers financing options for eligible new and used boats and personal watercraft. Your available APR, loan amount, and term will depend on your application and the watercraft being financed.
Check the live rate table before estimating your payment or applying. This gives you the most current published information instead of relying on a rate quoted in an older article or advertisement.
Advertised rates and terms are subject to change. Loan approval is subject to application, creditworthiness, membership eligibility, and collateral considerations. The lowest advertised APR may not be available to every borrower or for every watercraft.
Disclosures
*APR = Annual Percentage Rate. The actual APR and loan term are subject to approval and may be determined by the borrower’s creditworthiness, amount borrowed, and the type, value, age, and condition of the collateral offered to secure the loan, when applicable. Rates are effective as of today and are subject to change.
¹Special Loan Rate Discount: Benefit from a 0.25% reduction when enrolling in PDCU’s automatic-payment service, which is included in the “as low as” rate advertised. The discount is available to borrowers who set up automatic monthly loan payments from a People Driven Credit Union checking or savings account. Federally Insured by NCUA
John Scharff is the Digital Marketing Lead at People Driven Credit Union, where he helps create clear, practical financial content for members and the communities PDCU serves. He focuses on making financial topics easier to understand, from loans and savings accounts to digital banking, fraud prevention, and everyday money management.
View More Posts